

The government has notified the third phase of its Corporate Average Fuel Economy norms, setting progressively tighter fuel-efficiency requirements for passenger vehicle manufacturers from April 2027 while giving them several routes to comply, including higher weightage for electric and hybrid vehicles, benefits for alternative fuels, efficiency-technology credits and trading of compliance credits.
The final CAFE III framework will apply to M1 category passenger vehicles manufactured or imported for sale in India from April 1, 2027 to March 31, 2032, according to a Ministry of Power notification. The standards will continue to be calculated at the manufacturer level using the sales-weighted average fuel consumption of its vehicle portfolio.
CAFE III targets tighten through FY2032
*For a manufacturer with a reference fleet weight of 1,229kg
The permitted fleet-average fuel consumption will become progressively lower each year. The standard will be calculated using the formula a×(W−1,229)+c, where W represents the weighted average unladen mass of all eligible vehicles manufactured or imported for sale by an OEM.
For a manufacturer with a reference fleet weight of 1,229kg, the target falls from 3.996 litres of petrol equivalent per 100km in FY2028 to 3.3273 litres per 100km in FY2032. This corresponds to about 94.8g CO2/km in FY2028 and 78.9g/km in FY2032.
The targets are calculated across the manufacturer's eligible fleet, meaning sales of more efficient vehicles can offset higher-consuming models within the same portfolio. Small-volume manufacturers with annual eligible vehicle volumes below 1,000 units are exempt from meeting the specific CAFE target, although they will still have to report their average fuel-consumption performance.
EVs gain biggest advantage
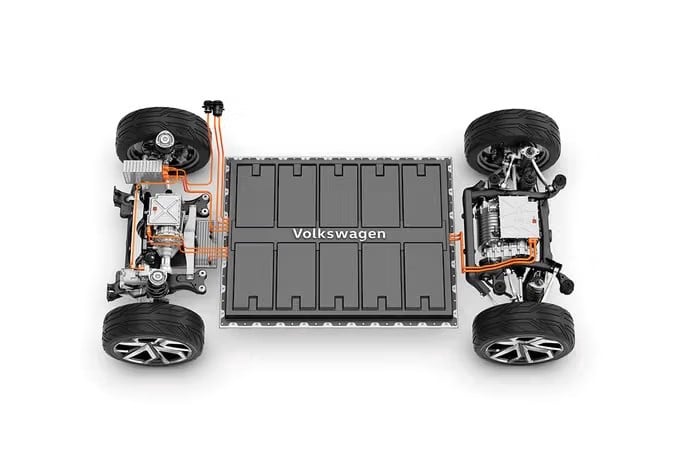
Battery electric vehicles and range-extended electric vehicles will receive a 3.0 super credit multiplier under CAFE III. Plug-in hybrids and flex-fuel strong hybrids get a 2.5 super credit multiplier, strong hybrids get a 1.6 and flex-fuel ethanol vehicles get a 1.1 super credit multiplier.
The final rules do not include the additional 3g CO2/km benefit for certain sub-four-metre petrol cars that had been proposed in an earlier draft of CAFE III.
CNG and ethanol also get benefits
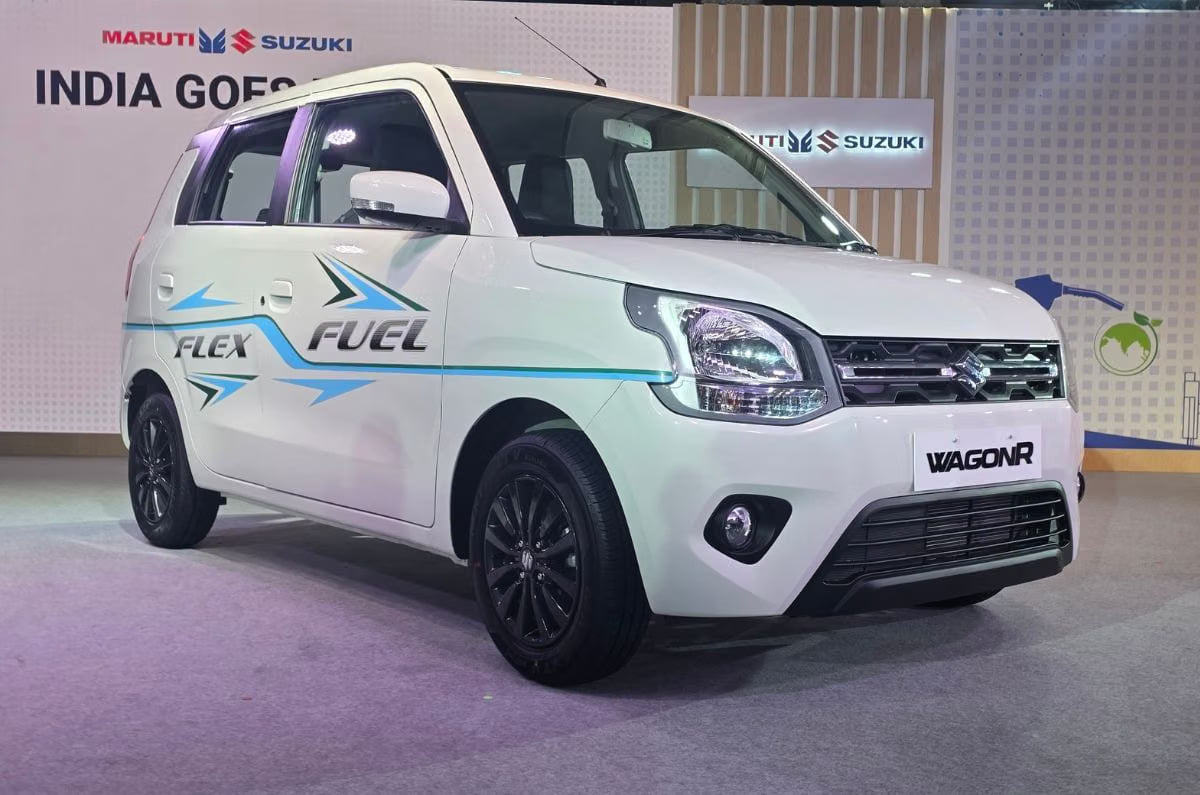
CAFE III also gives carmakers another route through what the government calls a Carbon Neutrality Factor for alternative-fuel vehicles. Cars running on E20 or higher notified ethanol-petrol blends, including strong and plug-in hybrids, get an 8 percent carbon-neutrality factor on tailpipe CO2.
Flex-fuel ethanol vehicles get a 22.3 percent carbon-neutrality factor, while CNG vehicles get 5 percent or the notified CBG blending percentage, whichever is higher. Diesel vehicles receive a benefit linked to the notified biofuel blending level.
The provision gives manufacturers another compliance route alongside electrification, with the benefits extending to CNG, ethanol and other alternative-fuel vehicles.
Carmakers can trade fuel-efficiency credits
One of the bigger structural changes under CAFE III is the formalisation of a credit-and-debit system that allows compliance performance to carry financial value. Manufacturers whose fleet performs better than their prescribed target will generate credits, while those exceeding their permitted fuel-consumption level will accumulate debits. These will be maintained in a manufacturer-specific compliance "passbook".
Surplus credits can be traded between manufacturers on mutually agreed terms. Carmakers can also buy credits from the Bureau of Energy Efficiency (BEE) to offset outstanding debits. The price rises from Rs 2,500 per g CO2/km in FY2028 to Rs 4,500 per g CO2/km in FY2032. The escalating price increases the incentive for companies to improve their underlying fleet performance.
The five-year CAFE III period will be split into two compliance blocks: FY2028-FY2030 and FY2031-FY2032. Credits and debits can be carried forward within each block, while unused credits will lapse at the end of the block.
Efficiency technologies also carry benefits
CAFE III allows manufacturers to claim a 1g CO2/km reduction for each eligible efficiency technology, subject to a maximum benefit of 9g CO2/km. The 12 eligible technologies include start-stop systems, tyre-pressure monitoring, regenerative braking, six-speed or higher transmissions, efficient alternators, motor-generators, LED exterior lighting, advanced glazing, electric water pumps and high-efficiency air-conditioning systems.
CAFE III introduces WLTP reporting
CAFE III also begins India’s transition towards using the Worldwide Harmonised Light Vehicles Test Procedure (WLTP) for corporate efficiency calculations. Manufacturers will have to declare the CO2 performance of models sold from April 1, 2027 under both the existing Modified Indian Driving Cycle (MIDC) and WLTP.
The conversion factor for translating the CAFE target from MIDC to WLTP will be notified separately by the Ministry of Power in consultation with the BEE. That leaves an important part of the implementation framework to be finalised despite the five-year CAFE III regime now being notified.
 Autocar India News Desk
 Uday Singh